The 4% Mortgage Is Back, But It Comes With a Catch
The 4% Mortgage Is Back, But It Comes With a Catch
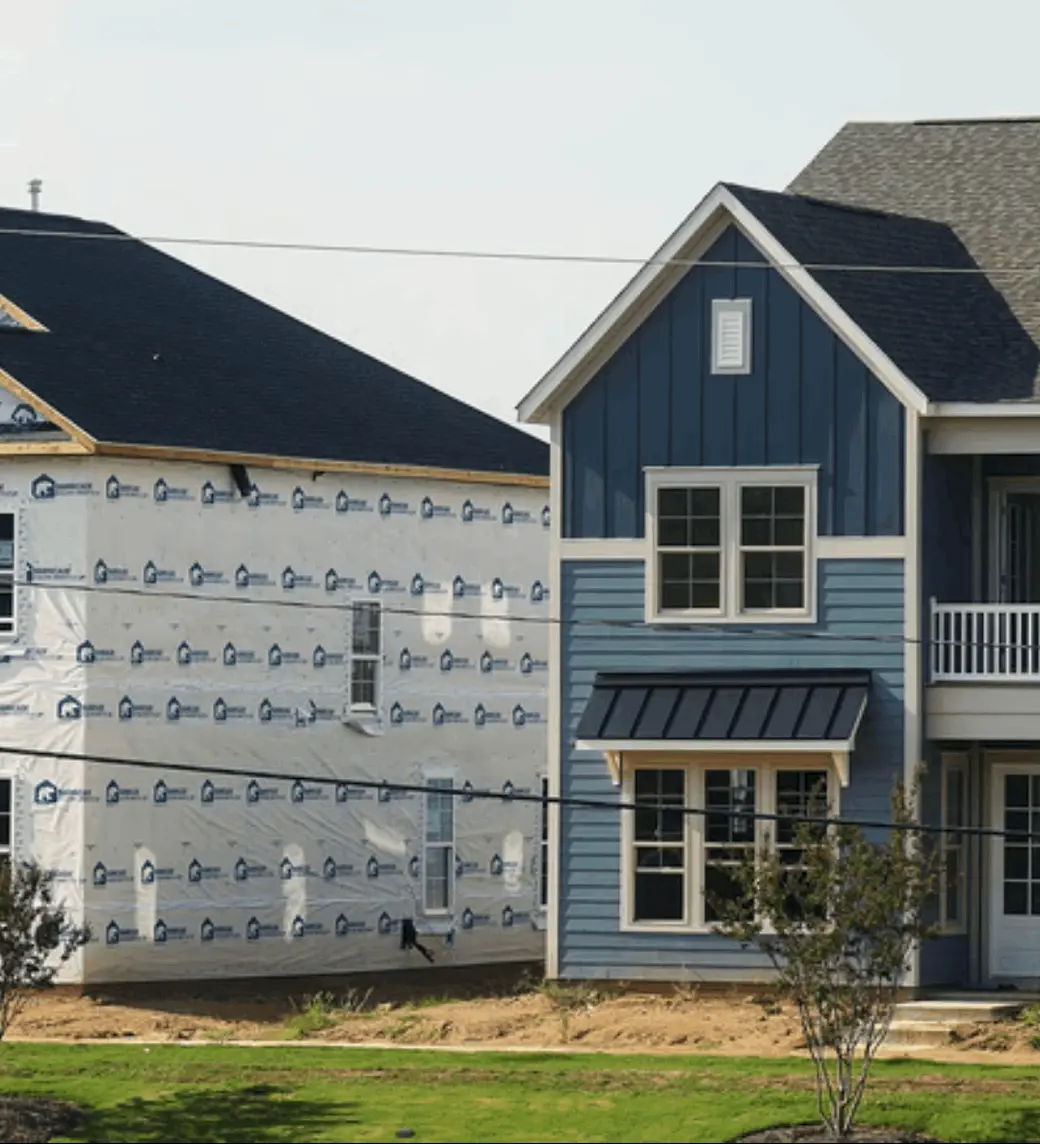
Builders are advertising something that sounds almost impossible right now: mortgage rates under 4%. According to Realtor.com, nearly 1 in 7 new-construction listings advertised a reduced interest rate in August, averaging 3.92%. Everyone else is paying 6.67% or higher, with rates climbing to 6.76% by Thursday, their highest point since June 2025.
"A sub-4% mortgage rate is extremely valuable, even for just a year or two, because it significantly cuts your early interest costs and builds home equity much faster," says Jeremy Olsher, a Florida real estate agent. On a median-priced $450,000 new home with 20% down, that rate gap works out to about $614 less per month, or nearly $7,400 a year.
Why builders are buying down rates instead of cutting prices
It's not generosity, it's math. Research from the American Enterprise Institute Housing Center found that reducing a mortgage rate by 1 percentage point costs a builder roughly 3.2% of the sale price. Getting the same reduction in monthly payment through a price cut would take a price drop of roughly 10%. The financing subsidy is expensive, but it's cheaper than the alternative.
Builders are spending heavily to make it work. Lennar's incentives averaged $62,700 per home in fiscal 2025, 13.8% of home-sale revenue, up from $42,900 two years earlier. PulteGroup's incentives hit 10.9% of gross sales price in the first quarter of 2026, up from 8% a year prior, and its gross margin dropped from 27.5% to 24.4% as a result.
The rates cluster where builders are fighting hardest for buyers
Reduced rates aren't spread evenly. Just 1.4% of new homes priced $100,000 to $200,000 advertised a lower rate, but that share climbed to 17.1% among homes priced $500,000 to $750,000. This is move-up territory, where buyers face the hardest trade-off: giving up a mortgage rate under 6%, which nearly 88% of existing homeowners still have.
The catch buyers need to understand
Joel Berner, senior economist at Realtor.com and author of the report, points out the risk directly. "If new-home prices get propped up by rate incentives, buyers paying the same monthly payment could have a larger loan balance on the discounted mortgage rate than they would have at a market mortgage rate," he says. If home prices fall after that, "this higher loan balance, if combined with falling home prices, could lead to buyers ending up underwater, owing more on their home than it's worth."
Appraisers are already being told to treat these buydowns carefully. Freddie Mac has warned appraisers that builders may use rate buydowns to "drive interest and support higher prices." Joseph Pravettone, chief appraiser at Atlas VMS, puts it plainly: "Incentives solve affordability today, but they can create equity, refinance, and resale problems tomorrow."
What this means whether you're buying or selling
If you're shopping new construction, a subsidized rate can be a genuinely good deal, but it's worth understanding what you're actually financing before you sign. If you own a resale home and you're up against new-construction competition down the street, you're now competing with incentives you can't easily match. Either way, this isn't a decision to make off a headline rate. Reach out and let's look at your specific numbers before you decide.
Categories
Recent Posts